MARKET UPATE [SEPT 2026]
Market Update / September 2026
Market Overview
September was characterized by a combination of persistent inflation, rising energy prices, increasingly restrictive monetary policy, and a sharp rise in long term bond yields, while economic growth remained relatively resilient. The escalation of the Middle East conflict and disruption risks around the Strait of Hormuz pushed Brent crude above $100 per barrel, contributing to higher inflation expectations and tighter financial conditions. U.S. CPI increased 3.4% year over year in August, while PCE inflation remained at 3.4%. Food prices also accelerated, with the FAO food price index rising 2.5% year over year. In response to renewed inflationary pressure, the Federal Reserve raised its policy rate to 3.75%–4.00% on September 16, its first increase since 2023, and projected another 25-basis point increase by year end. Despite the rate hike, economic activity remained firm, with U.S. Q2 GDP growth revised to 2.2%, consumer spending rising 0.9% in August, and weekly jobless claims remaining relatively low.
The most significant development for financial markets was the sharp increase in long term Treasury yields. The 10-year Treasury yield approached 5.2%, while the 30-year yield reached 5.59%, its highest level in roughly two decades. Higher energy prices, resilient economic data, expectations for additional Fed tightening, and substantial bond issuance associated with AI infrastructure investment all contributed to the selloff in longer duration government bonds. Mortgage rates consequently exceeded 7%, while higher discount rates increased pressure on equity valuations. U.S. equities experienced several periods of weakness during the month, although technology stocks rallied strongly at times as investors continued to price in substantial AI related investment and productivity growth.
Economic activity outside the U.S. remained relatively resilient. The OECD raised its 2026 global growth forecast to 2.9%, while eurozone business activity accelerated to its highest level in nearly 3.5 years and Chinese PMI data indicated improving activity across sectors. Japan's 10-year government bond yield reached 3.0%, while the Bank of Japan raised rates, reducing the relative attractiveness of U.S. assets for Japanese investors. Canada experienced weaker retail activity in July, although preliminary August data indicated a rebound, while inflation remained around 3%.
At the corporate level, cost pressures and weaker consumer demand remained evident in several consumer and service businesses. Lululemon reduced its outlook again, Campbell's announced significant workforce reductions, and Uber announced a 10% workforce reduction. IKEA, meanwhile, began cutting prices by 15%–25% on more than 1,500 products in Europe as consumers faced higher living costs. These developments suggest that companies exposed to discretionary consumption continue to face pressure from elevated prices and tighter household budgets.
Market Outlook
As expected, the United States implemented its first rate increase as inflation risks appeared to outweigh concerns about labour-market growth. This movement in the federal funds target reinforces our base case that we have built over the past few quarters, as the cost of capital has risen across global markets. Expectations for further rate increases have also shifted, as shown below

The red box highlights the federal funds rate and its implied probability at upcoming FOMC meeting dates. Based on our review of the late 1980s and the final stages of the 2000–01 dot-com bubble, they indicate the policy-rate levels most likely to materially affect equity markets. Although this remains a significant part of our outlook, noteworthy fundamental developments are also emerging, particularly in corporate earnings and profitability.
Below is our latest month-end estimate of the implied equity risk premium. Despite the market’s gains over the past few months, the premium increased over the same period, largely because expanding corporate profits enhanced returns to equity investors through dividends and share repurchases. This trend is notable when viewed alongside the recent earnings, dividend, and share-repurchase activity of the 500 largest U.S. companies, also presented below.


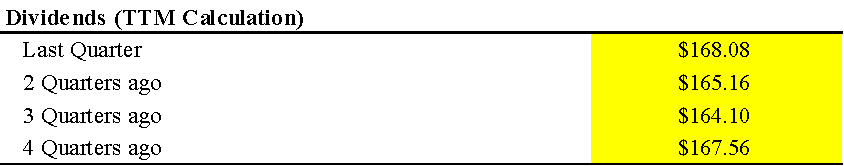

The data indicate that markets were overvalued relative to fundamentals, but fundamentals are now catching up with market expectations at a rapid pace. This has materially improved our assessment of broad equity downside risk. Notably, at the implied equity risk premium of 6.16%, a level that our historical analysis has identified as an attractive entry point for equities, downside risks seems much more manageable than what they looked like few months ago. This suggests that even if the market risk premium rose to historically favourable levels, implying a market correction for any reason, attractive fundamental buying opportunities would not be far from historical norms, with a potential decline of 19% to 20%.

Using 6.93% equity risk premium instead, a level generally associated with severe market crises, produced the following results.

Positively developing fundamental picture however, does not dismiss the fact that rising yields remain a risk to the markets. What this tells us instead is that investors should size their positions with the possibility of a 19% to 20% market decline from current levels in mind. Under the most severe scenario supported by historical measures, the decline could reach 27%. As long as these risks are understood and properly accounted for, we see no reason why U.S. equities cannot remain an attractive investment opportunity.
The key to monitoring these market conditions is determining whether corporate profits can continue to grow at a rapid pace. We must assess the returns generated by capital spending on AI infrastructure, whether stronger profits can support further increases in shareholder distributions, and how the small group of corporate managers that currently dominate the market will manage expectations that influence valuations.


Comments